Year-on-year inflation-indexed swap
| Part of a series on |
| Financial markets |
|---|
 |
| Bond market |
| Stock market |
| Other markets |
| Alternative investment |
| Over-the-counter (off-exchange) |
| Trading |
| Related areas |
A year-on-year inflation-indexed swap (YYIIS) is a standard derivative product over inflation rate. The underlying is a single consumer price index (CPI).[1] The first swap of this kind was traded through the inter-dealer broker network in November 1999.[2]
It is called a swap because each year there is a swap of a fixed amount against a floating amount, although in practice only a one way payment is made (fixed amount – floating amount).
Detailed flows
- Each year, at time
- Party B pays Party A the fixed amount
- Party A pays Party B the floating amount


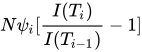
where:
- K is the contract fixed rate
- N the contract nominal value
- M the number of years corresponding to the deal maturity
- i the number of years (0 < i <= M)
- is the fixed-leg year fractions for the interval [Ti−1, Ti]
- is the floating-leg year fractions for the interval [Ti−1, Ti]
- is the start date
- is the time of the flow i
- is the maturity date (end of the swap)
- is the inflation at start date (time )
- is the inflation at time of the flow i (time )
- is the inflation at maturity date (time )


See also
References
- ↑ Cunningham, Rose; Desroches, Brigitte; Santor, Eric (2010). "Inflation Expectations and the Conduct of Monetary Policy: A Review of Recent Evidence and Experience". Bank of Canada Review (Spring 2010). Bank of Canada: 16. eISSN 1483-8303. ISSN 0045-1460.
- ↑ Deacon, Mark (2004). Inflation-indexed securities: bonds, swaps and other derivatives. Chichester, West Sussex, England: John Wiley & Sons. pp. 240–241. ISBN 978-0-470-86812-6.

Categories: