Statement of the theorem
Let C0 = C0([0, T]; Rd) be the Banach space of continuous functions 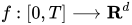 such that
 , equipped with the supremum norm ||⋅||∞ and
 be the subspace of absolutely continuous functions whose derivative is in
 (the so-called Cameron-Martin space). Define the rate function

on and let 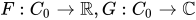 be two given functions, such that
 (the "action") has a unique minimum
 .
Then under some differentiability and growth assumptions on  which are detailed in Schilder 1966, one has

where  denotes expectation with respect to the Wiener measure
 on
 and
 is the Hessian of
 at the minimum
 ;
 is meant in the sense of an
 inner product.
Application to large deviations on the Wiener measure
Let B be a standard Brownian motion in d-dimensional Euclidean space Rd starting at the origin, 0 ∈ Rd; let W denote the law of B, i.e. classical Wiener measure. For ε > 0, let Wε denote the law of the rescaled process √εB. Then, on the Banach space C0 = C0([0, T]; Rd) of continuous functions such that , equipped with the supremum norm ||⋅||∞, the probability measures Wε satisfy the large deviations principle with good rate function I : C0 → R ∪ {+∞} given by
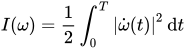
if ω is absolutely continuous, and I(ω) = +∞ otherwise. In other words, for every open set G ⊆ C0 and every closed set F ⊆ C0,

and
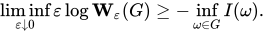
Example
Taking ε = 1/c2, one can use Schilder's theorem to obtain estimates for the probability that a standard Brownian motion B strays further than c from its starting point over the time interval [0, T], i.e. the probability
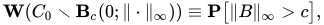
as c tends to infinity. Here Bc(0; ||⋅||∞) denotes the open ball of radius c about the zero function in C0, taken with respect to the supremum norm. First note that
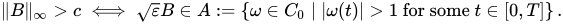
Since the rate function is continuous on A, Schilder's theorem yields

making use of the fact that the infimum over paths in the collection A is attained for ω(t) = t/T . This result can be heuristically interpreted as saying that, for large c and/or large T

In fact, the above probability can be estimated more precisely: for B a standard Brownian motion in Rn, and any T, c and ε > 0, we have:
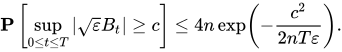
References
- Dembo, Amir; Zeitouni, Ofer (1998). Large deviations techniques and applications. Applications of Mathematics (New York) 38 (Second ed.). New York: Springer-Verlag. pp. xvi+396. ISBN 0-387-98406-2. MR 1619036. (See theorem 5.2)
