Definitions
The first definition[1] presented here is typically used in Analysis (harmonic analysis, Fourier Analysis, and integration theory in general) to analysis properties of functions.
Definition 1: Suppose

is a
measure space, and let

be a real-valued
measurable function. The distribution function associated with
is the function

given by

It is convenient also to define

.
The function  provides information about the size of a measurable function .
The next definitions of distribution function are straight generalizations of the notion of distribution functions (in the sense of probability theory).
Definition 2. Let

be a finite
measure on the space

of
real numbers, equipped with the
Borel  -algebra
. The
distribution function associated to
is the function

defined by
![{\displaystyle F_{\mu }(t)=\mu {\big (}(-\infty ,t]{\big )}}](./_assets_/eb734a37dd21ce173a46342d1cc64c92/6b27fa841ae4a9813b2d9cb4b5408140c88b3a12.svg)
It is well known result in measure theory[2] that if  is a nondecreasing right continuous function, then the function defined on the collection of finite intervals of the form
![{\displaystyle (a,b]}](./_assets_/eb734a37dd21ce173a46342d1cc64c92/6a6969e731af335df071e247ee7fb331cd1a57ae.svg) by
![{\displaystyle \mu {\big (}(a,b]{\big )}=F(b)-F(a)}](./_assets_/eb734a37dd21ce173a46342d1cc64c92/acd689ad4c91a0ce1d80453da0b070db389d5ff9.svg) extends uniquely to a measure
 on a -algebra
 that included the Borel sets. Furthermore, if two such functions
 and
 induce the same measure, i.e.
 , then
 is constant. Conversely, if is a measure on Borel subsets of the real line that is finite on compact sets, then the function
 defined by
![{\displaystyle F_{\mu }(t)={\begin{cases}\mu ((0,t])&{\text{if }}t\geq 0\\-\mu ((t,0])&{\text{if }}t<0\end{cases}}}](./_assets_/eb734a37dd21ce173a46342d1cc64c92/17d5ac9ab6b0aedb58ebf913070970fc27ab3839.svg) is a nondecreasing right-continuous function with
 such that
 .
This particular distribution function is well defined whether is finite or infinite; for this reason,[3] a few authors also refer to  as a distribution function of the measure . That is:
Definition 3: Given the measure space
, if
is finite on compact sets, then the nondecreasing right-continuous function
with

such that
![{\displaystyle \mu {\big (}(a,b])=F_{\mu }(b)-F_{\mu }(a)}](./_assets_/eb734a37dd21ce173a46342d1cc64c92/a415d706b2ef925ff156bd0532e527aad9aa69f8.svg)
is called the
canonical distribution function associated to
.
- The distribution function of a real-valued measurable function on a measure space is a monotone nonincreasing function, and it is supported on
 . If
 for some
 , then

- When the underlying measure on
 is finite, the distribution function in Definition 3 differs slightly from the standard definition of the distribution function (in the sense of probability theory) as given by Definition 2 in that for the former, while for the latter,
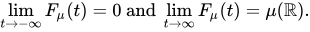
- When the objects of interest are measures in , Definition 3 is more useful for infinite measures. This is the case because
![{\displaystyle \mu ((-\infty ,t])=\infty }](./_assets_/eb734a37dd21ce173a46342d1cc64c92/26e12e31871d623030e0719ae6c8885b377bc43b.svg) for all
 , which renders the notion in Definition 2 useless.
References
- ↑ Rudin, Walter (1987). Real and Complex Analysis. NY: McGraw-Hill. p. 172.
- ↑ Folland, Gerald B. (1999). Real Analysis: Modern Techniques and Their Applications. NY: Wiley Interscience Series, Wiley & Sons. pp. 33–35.
- ↑ Kallenberg, Olav (2017). Random Measures, Theory and Applications. Switzerland: Springer. p. 164. doi:10.1007/978-3-319-41598-7. ISBN 978-3-319-41596-3.

![{\displaystyle \lambda ((0,t])=t-0=t{\text{ and }}-\lambda ((t,0])=-(0-t)=t}](./_assets_/eb734a37dd21ce173a46342d1cc64c92/e43984f198d47e168b00452b8bcbcf0b85d31eff.svg)
